
The Top Weather-Related Insurance Claims in Every U.S. State
- CP Insurance Associates

- Jun 1
- 4 min read
Extreme weather is no longer considered “rare.” From billion-dollar hurricanes to devastating hailstorms and wildfires, weather-related insurance claims are increasing across the United States every year.
A homeowner in Texas may worry about hail damage, while someone in California is more concerned about wildfires and mudslides. In the Midwest, tornadoes dominate claims, and northern states continue to battle costly winter storm damage.
Using regional climate trends, FEMA National Risk Index data, NOAA disaster reporting, and insurance industry claim patterns, we analyzed the top five weather-related damages most commonly associated with insurance claims in each state.
Why Weather Claims Matter More Than Ever
According to NOAA, the United States now experiences dozens of billion-dollar weather disasters every year. Severe storms, flooding, hurricanes, and wildfires continue driving insurance losses higher nationwide.
For homeowners and lenders alike, understanding local weather risks helps:
Improve insurance coverage decisions
Reduce uncovered losses
Strengthen property protection planning
Identify regional risk exposure trends
The reality is simple: weather risk is highly regional.
Key industry sources used include NOAA, FEMA National Risk Index, and LexisNexis catastrophe claim reporting.
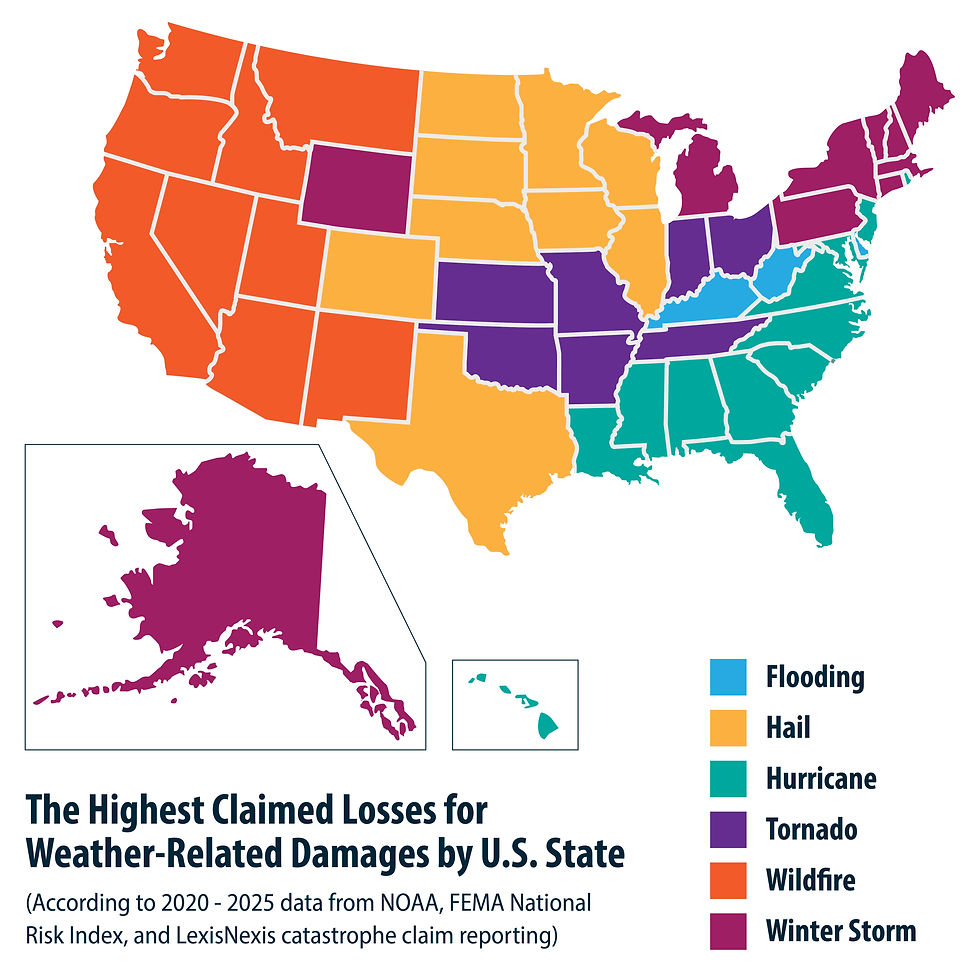
Regional Weather Risks Across the U.S.
Gulf Coast & Southeast: Hurricanes and Flooding Dominate
States along the Gulf Coast and Southeast consistently report the highest frequency of hurricane-related claims. Wind damage, storm surge flooding, and tornado activity often occur together during major tropical systems.
Most Common Claims in the Southeast:
Hurricane wind damage
Flooding
Tornado damage
Lightning strikes
Windstorm roof claims
High-Risk States:
Florida
Louisiana
Mississippi
Alabama
South Carolina
North Carolina
In Florida alone, hurricanes and water intrusion claims represent some of the most expensive homeowner losses in the country.

Midwest & Plains States: Hail and Tornado Alley
The central United States experiences some of the nation’s highest severe convective storm activity. Hailstorms and tornadoes generate billions in insured losses annually.
Most Common Claims in the Midwest:
Hail damage
Tornado damage
Straight-line wind damage
Flooding
Lightning claims
States with Major Hail Exposure:
Texas
Oklahoma
Kansas
Nebraska
Colorado
Iowa
Hail claims are especially expensive because they impact roofs, siding, windows, vehicles, and HVAC systems simultaneously.
Western States: Wildfire Risk Continues to Grow
Wildfires have become one of the largest catastrophe concerns for insurers in the western U.S. In states like California, Oregon, and Washington, wildfire exposure has reshaped underwriting guidelines and property eligibility.
Most Common Western Weather Claims:
Wildfire damage
Smoke damage
Mudslides after burn scars
Windstorm claims
Flash flooding
Highest Wildfire Exposure States:
California
Oregon
Washington
Arizona
Nevada
Idaho
Many western homeowners are now seeing rising premiums, stricter inspections, and increased non-renewal activity due to wildfire exposure.
Northern States: Winter Storms and Ice Damage
In northern regions, winter weather remains a major source of property damage. Heavy snow loads, frozen pipes, ice dams, and wind-driven snow events create costly seasonal claims.
Common Winter Weather Claims:
Roof collapse from snow
Frozen pipe water damage
Ice dam leaks
Windstorm damage
Winter-related flooding
High Winter Risk States:
Minnesota
Wisconsin
Michigan
New York
Vermont
Maine
Even relatively small winter losses can become expensive due to water intrusion and mold remediation.
Texas: One of the Most Complex Weather Risk States
Texas stands out because it experiences nearly every major weather peril:
Hailstorms
Hurricanes
Tornadoes
Flash flooding
Severe wind events
This combination makes Texas one of the most active insurance claim environments in the country. Large hail losses in cities like Dallas–Fort Worth routinely produce widespread roof replacement claims.
The Top 5 Weather-Related Insurance Claims by State
Below is a PDF that captures the top 5 weather-related risks by state:
How Homeowners Can Reduce Weather-Related Losses
While weather cannot be prevented, damage can often be minimized with proactive preparation.
Recommended Risk Mitigation Steps
Schedule annual roof inspections
Trim trees near structures
Install impact-resistant roofing where appropriate
Review flood insurance eligibility
Maintain proper drainage around foundations
Winterize exposed plumbing
Create wildfire defensible space in high-risk zones
Many insurers also offer discounts for mitigation improvements.
Final Thoughts on the Top Weather-Related Insurance Claims in U.S. States
Weather-related insurance claims are becoming more frequent, more severe, and more expensive nationwide. Understanding the specific risks in your state can help homeowners make smarter coverage decisions and prepare for future disasters.
Whether the threat is hurricanes in Florida, hailstorms in Texas, or wildfires in California, one thing is clear: localized risk matters more than ever in today’s insurance landscape.
For lenders and financial institutions, these weather risks also represent growing portfolio exposure. Properties impacted by uninsured or underinsured losses can increase default risk, create collateral deterioration, and complicate servicing operations after catastrophic events. As climate-driven weather events continue to intensify, proactive insurance tracking and collateral protection strategies are becoming essential components of portfolio risk management.
At CPIA, we help lenders protect their portfolios through specialized collateral protection insurance services and insurance tracking solutions designed to identify coverage gaps before losses occur. By combining industry expertise with responsive servicing and technology-driven monitoring, CPIA supports lenders in reducing exposure, maintaining compliance, and safeguarding asset performance in an increasingly unpredictable weather environment.


https://ko66a.uk.com/ làm mình thấy rõ hơn phạm vi nội dung khi mỗi lần chuyển khu đều xuất phát từ một nhu cầu mới. Mình có thể xem Baccarat trong Casino, sau đó tìm sang thể thao để theo dõi bóng rổ rồi kết thúc ở game bài với Phỏm. Mình không cố tạo mối liên hệ giữa ba nội dung mà chủ yếu quan sát cách chúng được phân thành những khu riêng và cách mình tìm lại từng khu. Sau nhiều lượt chuyển, menu chung dần trở thành điểm định hướng quen thuộc mỗi khi mục đích thay đổi. Với mình, hệ sinh thái dễ hiểu nhất khi mình biết từng nhu cầu nên bắt đầu ở đâu, thay vì…
cm88 qua một thời gian đã trở thành cái tên khá quen, dù mỗi lần quay lại mình không nhất thiết quan tâm đến cùng một nội dung. Mình đã có những giai đoạn sử dụng chủ yếu trên điện thoại và những lúc khác chuyển sang máy tính. Nổ hũ từng là lựa chọn khá quen, còn bắn cá xuất hiện thêm khi sở thích thay đổi. Thiết bị thường được mình chọn theo hoàn cảnh chứ không gắn với một khu cụ thể. Sau nhiều lần sử dụng, cả hai cách truy cập đều trở nên quen và mình chủ yếu chú ý đến nội dung đang muốn trải nghiệm.
Khi phân tích new88 từ góc độ thao tác, mình thấy hệ thống được xây theo hướng giảm bớt bước tìm kiếm cho người dùng. Slot game, thể thao và hướng dẫn sử dụng được phân thành các khu khá rõ, giúp việc chọn nội dung diễn ra nhanh hơn. Mình thử nhìn cách phần hướng dẫn hỗ trợ người mới khi chuyển qua các chuyên mục chính, cảm giác khá hợp lý. Các khu không bị đặt quá xa nhau nên mạch sử dụng vẫn giữ được sự liền mạch. Ngoài ra, phản hồi nhanh giúp thao tác không bị kéo dài. Với mình, hệ thống tốt là hệ thống làm cho người dùng hiểu được đường đi chỉ sau…
From a practical standpoint Visa is one of the more predictable payment options for Norwegian users, mostly because the infrastructure is old, widely tested and integrated with almost every bank. Transactions usually clear fast, and the fraud monitoring is decent, though nothing replaces a careful user. For anyone comparing options it makes sense to look at neutral overviews such as casinonorskvisa.no and cross reference the terms with the actual bank conditions, since fees can differ per issuer. Withdrawals are not always as instant as advertised, so expectations should stay realistic. Overall a stable method, but not magic. Just a personal observation, not advice, so treat any online financial activity with caution and rely on verified information before making decisions.